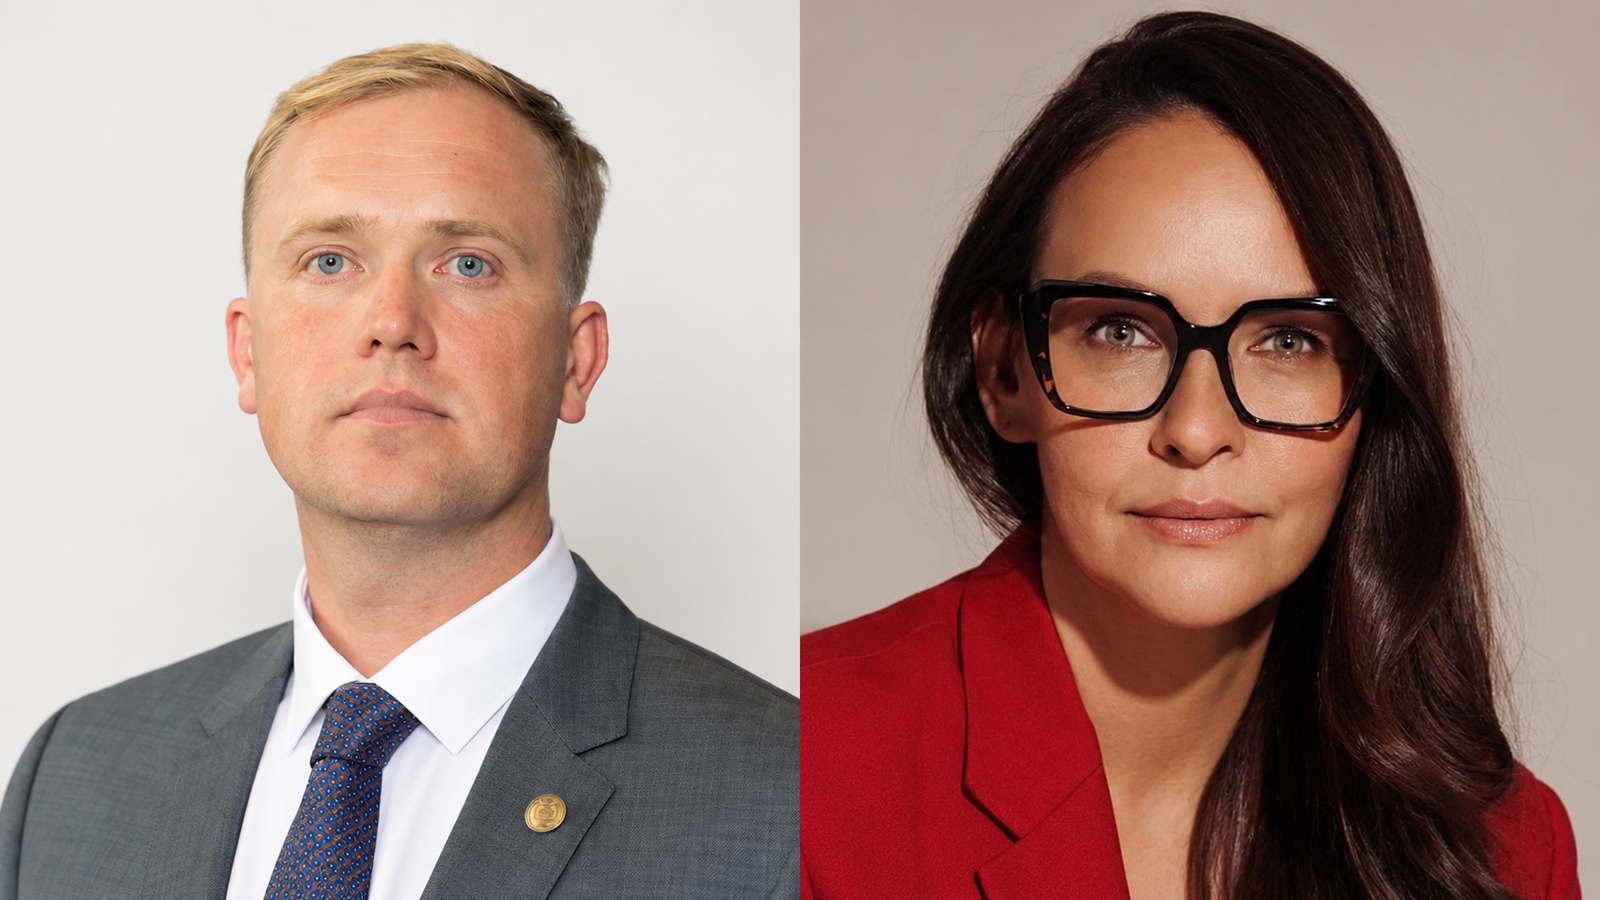
By Viktors Valainis, Minister of Economics of the Republic of Latvia & Tīna Lūse, Head of Fintech Latvia Association.
Over the past decade, Europe’s financial technology, or fintech, sector has become one of the fastest-growing parts of the economy. It creates well-paid jobs, attracts international capital and promotes innovation in the financial sector. The Baltic states have already demonstrated that even a small country can become a significant player in this market. The question is whether Latvia will seize its opportunity.
Lithuania previously set a deliberate ambition to become one of Northern Europe’s leading fintech hubs. This approach produced results: international companies such as Revolut and Binance entered the country, while many people in Latvia now use financial solutions established in Lithuania, including Revolut and Paysera. The development of fintech became one of the factors that helped Lithuania consolidate its leading position in the Baltic region.
Latvia now has an opportunity to capitalise on its own advantages. Following the geopolitical changes of 2022, investors have become considerably more cautious when assessing long-term investments in the region. It is therefore particularly important to attract industries that can generate economic value in the near term by creating well-paid jobs, exporting services and paying taxes. Fintech is one such industry.
The restructuring of Latvia’s financial sector has also made an important contribution. Only a few years ago, Latvia was internationally associated with reputational challenges, whereas today its licensing and supervisory system is regarded as professional and reliable. This sends an important signal of quality to companies choosing where to establish their operations within the European Union.
Latvia has already developed a specialisation in peer-to-peer lending and alternative finance. One prominent example is Mintos, a company founded in Latvia whose business model is based on attracting international investors and operating in global markets. Highly skilled jobs, tax revenue and technological expertise remain in Latvia. One successful company encourages others to choose Latvia as well, and several businesses have already followed its example.
Today, fintech in Latvia is no longer merely a promising industry—it is already a significant part of the national economy. Latvia is home to 127 fintech companies employing more than 3,600 people. Their combined turnover is approaching €400 million, while they contribute more than €91 million in taxes to the state budget every year.
These results provide a foundation for more ambitious goals. Latvia’s Fintech Development Strategy aims to increase the number of fintech companies registered in the country by 30%, raise the volume of attracted investment by 15% and increase employment in the sector by 18%. This would mean more exports, more well-paid jobs and higher tax revenue for the state budget.
At the same time, Latvia should learn from Lithuania’s experience. Lithuania’s success was driven not only by its international visibility but also by practical support for innovation. Public-sector instruments helped mobilise private capital and develop alternative financing solutions.
Latvia’s next step should therefore be not only to maintain predictable regulation and efficient licensing, but also to consider introducing similar support instruments for licensed peer-to-peer lending and crowdfunding platforms. Public participation or co-financing through selected instruments could help attract private capital, expand companies’ access to finance and accelerate investment in productive projects, including real estate development. The objective is not to replace private capital, but to activate it and strengthen Latvia’s capital market. It is estimated that if the state participated as a co-investor with €20 million, this could attract or generate an economic benefit of €100 million within several years.
Billions of euros are currently held in current accounts or deposits at Latvian banks without fully contributing to the development of the Latvian economy, as banks’ risk appetite does not correspond to the level required. If the state set an example for private investors with the support of ALTUM, it would provide an additional and necessary stimulus for faster economic development in other sectors.
People now use financial services differently from the way they did a decade ago. A single bank is no longer the only solution: consumers also use a variety of applications for payments, savings and investments. This is precisely the market segment in which Latvia has an opportunity to strengthen its position.
Our task is to ensure that companies seeking to develop innovative financial services for Europe and the world see Latvia as their first choice. This requires competitive regulation, efficient licensing, targeted investment attraction and close cooperation between the government and the industry. If we can provide these conditions, fintech can become one of the pillars of Latvia’s economic growth over the next decade.