The PONAR Group is expanding its operations in the defence sector and advanced industrial solutions, supplying proprietary technologies and products for key military platforms, including the KRAB self-propelled howitzer, the BORSUK infantry fighting vehicle, the POPRAD surface-to-air missile system, and the BYSTRA and P-18PL radar systems. In 2025, the Group’s revenue increased by 40.8% year-on-year to PLN 351.9 million, with an operating profit margin of 19.4%. In the first half of 2026, revenue growth accelerated to 59.3% year-on-year, with an operating profit margin of 22.8%. The Group’s further development is expected to be supported by its growing order backlog, the expansion of its defence operations, international expansion, and the development of new capabilities and products, including the launch of production of armaments such as self-propelled howitzers and 155 mm artillery projectiles.
Key Information on the Offering
The planned Offering will comprise the issuance of new shares by the Company (representing up to 5% of its share capital) and the sale of portions of existing shareholdings by certain shareholders.
PONAR expects the gross proceeds from the issuance of new shares to be used to support the Group’s further development, in particular to:
pay the third and final instalment of the purchase price for the acquisition of a 51% stake in CASP System sp. z o.o., completed in the first half of 2026. CASP System specialises in non-destructive testing (NDT) and industrial automation solutions;
provide additional equity funding to PK MIL, a joint venture with the Kramatorsk Heavy Duty Machine Tool Building Plant, which is preparing to launch the production of 155 mm BOGDANA howitzers in Poland;
strengthen the Company’s working capital to maintain flexibility in pursuing strategic opportunities that may accelerate expansion in the Group’s existing or new areas of business.
The Offering is expected to be addressed to retail and institutional investors in Poland, as well as selected international institutional investors outside the United States of America and Poland, in accordance with Regulation S under the US Securities Act of 1933, as amended.
The Company, the Selling Shareholders and the Joint Global Coordinators intend to allocate approximately 5% of the total number of shares ultimately offered in the Offering to retail investors.
The Company is currently indirectly controlled by Marek Warzecha, President of the Management Board, who, through MW ONE sp. z o.o. (“MW ONE”) and the Marek Warzecha Family Foundation, holds shares representing an aggregate of 46.1% of the Company’s share capital and carrying 56.9% of the total voting rights at the General Meeting. The second-largest shareholder is VALUE FIZ, holding 44.5% of the share capital and 35.6% of the voting rights.
Following completion of the Offering, Marek Warzecha, President of the Management Board, will remain the controlling shareholder of PONAR. MW ONE and the Marek Warzecha Family Foundation will undertake not to dispose of their shares for a period of 720 days from the first day of trading of the Company’s shares on the WSE. In the case of VALUE FIZ, the lock-up period will be 270 days, while the Company and the third Selling Shareholder will be subject to lock-up periods of 360 days. In addition, the remaining shareholders holding shares prior to the Offering intend to enter into lock-up undertakings restricting the disposal of the Company’s shares for a period ending 90 days after the first day of trading of the Company’s existing shares or rights to shares, if admitted to trading on the WSE.
IPOPEMA Securities S.A. and Pekao Investment Banking S.A. are acting as Joint Global Coordinators and Joint Bookrunners. Bank Polska Kasa Opieki S.A. – Biuro Maklerskie Pekao is acting as Joint Bookrunner, while Trigon Dom Maklerski S.A. is acting as Co-Manager of the Offering. Bank Polska Kasa Opieki S.A. – Biuro Maklerskie Pekao and IPOPEMA Securities S.A. are also acting as Investment Firms intermediating in the Offering and as Offering Agents.
cc group sp. z o.o. and Inner Value sp. z o.o. are acting as advisers to the Management Board and as investor relations and public relations advisers.
Rymarz, Zdort, Maruta, Wachta, Gasiński, Her i Wspólnicy sp.k. is acting as Legal Adviser to the Company and the Selling Shareholders, while White & Case M. Studniarek i Wspólnicy Kancelaria Prawna sp.k. is acting as Legal Adviser to the Joint Global Coordinators, Joint Bookrunners and Co-Manager of the Offering.
The detailed terms and conditions of the Offering will be set out in the Prospectus, which will be published in accordance with applicable laws and regulations following its approval by the Polish Financial Supervision Authority (Komisja Nadzoru Finansowego, “KNF”).
Key Highlights of the PONAR Group
Over 60 years of experience and a unique dual-use business model. The PONAR Group is one of Poland’s largest manufacturers of hydraulic components and systems and one of Europe’s technology leaders in dual-use hydraulic power solutions. The Group leverages its expertise and manufacturing capabilities to serve both the defence and civilian sectors, enabling it to diversify its revenue streams and make more efficient use of investments in new product development. The PONAR Group intends to continue developing its technologies and product portfolio for both the defence and civilian sectors in parallel.
A key supplier of mission-critical components to the Polish defence industry. The Group’s hydraulic solutions are used in a range of military platforms, including KRAB self-propelled howitzers, BORSUK infantry fighting vehicles, specialised JELCZ wheeled platforms, BYSTRA and
P-18PL radar systems, and POPRAD surface-to-air missile systems. PONAR is the only Polish manufacturer and one of the few European manufacturers capable of independently designing, developing and prototyping hydropneumatic suspension modules for combat vehicles, followed by their serial production and delivery. The Group’s products have demonstrated their effectiveness under actual combat conditions and have achieved combat-proven status.
A broad and diversified customer base comprising over 3,000 customers in more than 80 countries. The Group supplies solutions to both the defence sector, serving, among others, companies within the Polish Armaments Group (PGZ) and private-sector entities, and the civilian sector, providing solutions for industries including machinery manufacturing, rail transport, energy, aerospace, mining, maritime and offshore.
Significant exposure to international markets, which account for more than half of the Group’s revenue. In 2025, export sales represented 53.2% of the Group’s revenue, confirming its strong position in European and global markets.
Dynamic and profitable growth. In the first half of 2026, revenue increased by 59.3% year-on-year to PLN 244.8 million, with an operating profit margin of 22.8%. In 2025, the Group’s revenue grew by 40.8% year-on-year to PLN 351.9 million, while net profit attributable to shareholders of the parent company increased by 31.0% year-on-year to PLN 45.7 million. This strong financial performance has been accompanied by a high conversion of EBITDA into operating cash flow.
High visibility of future revenue supported by a substantial order backlog. As at 30 September 2026, the Group’s total reported backlog amounted to PLN 1.7 billion, comprising signed contracts worth PLN 1.3 billion (fixed backlog) and expected orders under the SAFE programme worth nearly PLN 390 million (SAFE-related backlog). The Group does not include potential orders arising from contracts at various stages of negotiation in its reported backlog. As at that date, approximately 31% of the reported backlog was attributable to Q4 2026–2027, approximately 37% to 2028–2029, and the remaining approximately 32% to 2030 and subsequent years.
Growing revenue potential throughout the product lifecycle. The expanding installed base of PONAR systems, anticipated further orders for military platforms and increasing equipment utilisation are generating long-term demand for maintenance services, overhauls, spare parts and upgrades. This creates opportunities to generate aftermarket revenue throughout the entire service life of the equipment, which may extend to 30–40 years.
Armaments production as a new pillar of the Group’s growth. PONAR is at an advanced stage of preparing two initiatives that are expected to expand the Group’s business model by introducing a key new growth pillar: the production of selected types of armaments. Both initiatives are being developed through joint ventures with reputable external partners contributing financial resources as well as technological and manufacturing expertise. Through PK MIL, a joint venture with the Kramatorsk Heavy Duty Machine Tool Building Plant in which the Group holds a 51% equity stake, preparations are underway to launch production of 155 mm BOGDANA self-propelled howitzers in Poland from 2028, primarily for export markets. In turn, Polska Amunicja, jointly controlled through WPT Holding by PONAR and WB Electronics, Poland’s largest privately owned defence company, is expected to commence production of complete 155 mm artillery projectiles around the turn of 2027 and 2028. The Group is actively pursuing contracts for both categories of armaments, representing additional potential for order backlog growth that is not reflected in its currently reported value.
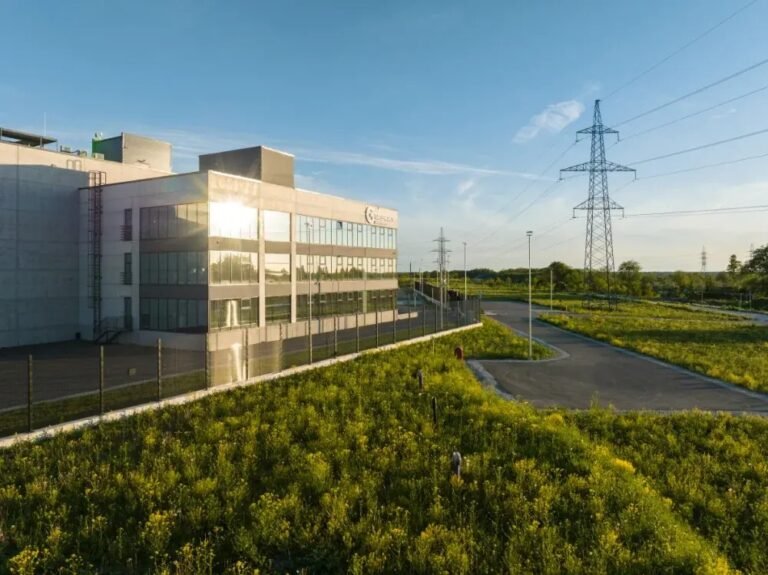
A scalable industrial platform developed through organic growth and acquisitions. The Group operates five manufacturing facilities (in Wadowice, Łaziska Górne, Lubań, Ostrów Wielkopolski and Jaworzno), its own research and development centre (CBR PONAR), and employs a team of approximately 170 engineers and technical specialists. The acquisitions of ZAP-Mechanika and CASP System have enabled the Group to expand its existing precision metal machining capabilities and acquire new expertise in advanced non-destructive testing, strengthening its ability to develop complementary business areas.
Domestic and international partnerships. The Company is developing industrial and technological partnerships with key players in the defence and civilian sectors, including:
Polska Grupa Zbrojeniowa (PGZ) and Jelcz – a tripartite agreement covering the development, design, integration, implementation and production of wheeled and automotive platforms, as well as the technologies and components constituting their key subsystems.
Moog Inc. (USA) – a technology cooperation agreement in the aerospace and defence sectors.
MNC Solution (South Korea) – a strategic partnership to assess the feasibility of launching production of advanced drive systems and hydraulic systems for K2 and K9 platforms in Poland.
Szczęśniak Pojazdy Specjalne – a partnership covering the selection, supply, adaptation and integration of vehicle platforms for self-propelled artillery systems.
Hellenic Vehicle Industry ELVO 2020 S.A. – a letter of intent with the Greek manufacturer of civilian and military vehicles, establishing a framework for technological and industrial cooperation.
Łukasiewicz Research Network – a strategic partnership agreement covering the development, construction, integration and implementation of hydraulic power solutions, hydraulic systems and related technologies, as well as research and development activities.
Financial targets and dividend policy.
In the short term, the Management Board aims to maintain the Group’s strong growth momentum and achieve consolidated annual revenue of approximately PLN 500–550 million. In the medium term, the Management Board targets a compound annual growth rate (CAGR) of the Group’s consolidated revenue (calculated relative to the 2025 financial year and excluding PK MIL and Polska Amunicja) in the low twenties percentage range. At the same time, the Management Board aims to maintain the Group’s annual consolidated EBIT margin (excluding PK MIL and Polska Amunicja) at a level similar to that achieved in the Group’s most recent reporting period, in both the short and medium term, and for PK MIL to achieve an annual EBIT margin in the medium term comparable to that generated by the Group’s core business operations. Furthermore, assuming the Management Board’s expectations are met, the PK MIL initiative could generate estimated annual sales of approximately PLN 1.3–1.5 billion in the medium term (assuming the production and sale of approximately 100 howitzers per year), with these figures presented on a gross basis, without adjustment for the Group’s ownership interest in the venture. The achievement of the targeted growth objectives, including the development of new business initiatives, is expected to translate into improved financial performance for the Group, with the Company intending to share the resulting profits with its shareholders. The Management Board intends to recommend the payment of dividends amounting to at least 40% of the Group’s consolidated net profit.
“PONAR is entering a period of unprecedented growth opportunities in its history. Years of investment in technology, in-house engineering expertise and manufacturing capacity have enabled us to establish a strong position in the Polish defence industry. Rising defence expenditure, the need to expand Europe’s industrial capabilities and the development of more resilient and secure supply chains are opening up further growth opportunities for the Group. We intend to capitalise on this potential to further scale up our operations, both by expanding our existing product portfolio and pursuing new projects, including the production of 155 mm artillery systems through PK MIL and artillery projectiles through Polska Amunicja. The IPO is intended to support the execution of these plans and the continued creation of value at PONAR,” says Marek Warzecha, President of the Management Board and principal shareholder of PONAR Wadowice S.A.
PONAR Group’s Business Operations
The PONAR Group is one of Poland’s largest manufacturers of hydraulic components and systems and one of Europe’s leading providers of advanced dual-use hydraulic power solutions. The PONAR Group’s products and services are used across a wide range of civilian industries, including aerospace, rail transport, maritime and offshore, and energy, as well as in the defence sector. Drawing on more than 60 years of experience and know-how, the PONAR Group designs, develops and manufactures highly specialised components and complete hydraulic systems that form an integral part of modern industrial and military platforms. The PONAR Group adopts a comprehensive approach to customer relationships, covering the entire process from analysing customer requirements, through design, testing and certification, to the launch of serial production, complemented by full aftermarket support and maintenance services.
The PONAR Group operates in two sectors: defence and civilian. Manufacturing activities across these sectors are closely interconnected. Experience gained in civilian industries drives innovation and the development of solutions for defence applications, while military technologies, such as hydropneumatic suspension systems, may subsequently be adapted for civilian applications. Through its dual-use products and services, the Group is able to achieve high operational efficiency, particularly when adapting products developed for one sector to meet the requirements of the other.
In recent years, the PONAR Group has expanded its capabilities in both the defence and civilian sectors, including through the acquisitions of CASP System and ZAP-Mechanika and participation in joint venture projects.
The PONAR Group operates its own research and development centre, CBR PONAR, enabling it to independently design, test and develop new solutions and rapidly adapt existing products to the requirements of specific customers and platforms. Its in-house engineering expertise shortens the time required to move from concept and prototype to implementation and serial production, enhancing operational flexibility and responsiveness to changing market needs. The ability to rapidly develop and modify products without relying on external technological resources represents a significant competitive advantage for the Group, particularly in the defence sector.
Strong Position of the PONAR Group in the Defence Sector
The PONAR Group is one of the key suppliers of advanced hydraulic power solutions to the defence sector in Poland. The Group’s product portfolio includes complete hydraulic systems, hydropneumatic suspension systems and solutions responsible for the stabilisation, positioning and operation of critical components of military platforms, designed to meet the specific technical requirements of individual customers. To date, the Group has supplied approximately 650 different parts and components for 12 military platforms, including the KRAB self-propelled howitzer, the BORSUK infantry fighting vehicle, the POPRAD surface-to-air missile system and various radar systems. PONAR is the only Polish manufacturer and one of the few European manufacturers capable of independently developing, manufacturing and delivering hydropneumatic suspension modules for combat vehicles on a serial production basis.
The PONAR Group operates in the defence sector under a range of licences and certifications confirming compliance with national, international and industry-specific regulations and standards, particularly in the areas of quality, safety and authorisation to conduct regulated activities. The Company has a comprehensive, multi-level certification framework covering international standards (ISO), NATO standards (AQAP), product certifications (PED, ATEX) and regulatory authorisations, including the Internal Control System (Wewnętrzny System Kontroli – WSK) and a licence issued by the Polish Ministry of the Interior and Administration (MSWiA). In the Management Board’s opinion, the PONAR Group ranks among companies demonstrating a high level of quality and technological maturity in their products and services and is among the manufacturers capable of executing contracts subject to stringent military, industrial and security requirements.
The PONAR Group’s products are used in key programmes aimed at modernising and expanding the capabilities of the Polish Armed Forces, including the Technical Modernisation Plan for 2021–2035 and the SAFE programme (an EU financial instrument worth up to EUR 150 billion, designed to provide EU Member States with long-term loans for defence investments and procurement, with particular emphasis on joint procurement and strengthening the European defence industrial base), which forms part of the ReArm Europe package. Poland’s allocation under the SAFE programme amounts to EUR 43.7 billion, of which 89% is expected to be directed to the Polish defence industry. The PONAR Group supplies components for, among others, the following programmes covered by SAFE financing: (i) the programme involving the development of KRAB self-propelled howitzers and (ii) the programme involving BORSUK infantry fighting vehicles.
As mentioned above, the PONAR Group is also expanding its activities in (i) artillery systems (the BOGDANA self-propelled howitzer) through PK MIL, a joint venture between the PONAR Group and the Kramatorsk Heavy Duty Machine Tool Building Plant, and (ii) the production of 155 mm artillery ammunition through the Polska Amunicja project, developed in cooperation with WB Electronics.
PONAR Group’s Operations in the Civilian Sector
The PONAR Group’s offering in the civilian sector is built around an extensive portfolio of hydraulic components and systems used across a wide range of industries.
The product portfolio includes hydraulic systems, directional control valves and other hydraulic valves, pumps and motors, hydraulic cylinders, accumulators, filters, coolers and quick-release couplings. The Group also offers solutions designed to operate under demanding conditions, including potentially explosive atmospheres (with certification confirming compliance with the requirements of the ATEX Directive) and temperatures below -40°C, such as those encountered in Arctic environments. In addition, the Group designs bespoke hydraulic systems tailored to individual customer requirements.
The breadth of its product portfolio and its ability to adapt solutions to specific customer requirements enable the Group to serve a diverse range of industrial segments. In 2025, the civilian industries accounting for the largest shares of the Group’s sales were industrial machinery, mining and rail transport, while in the first half of 2026 they were industrial machinery, mining, and municipal and agricultural and forestry machinery.
PONAR Group’s Strategy
The PONAR Group’s strategy is based on a unique business model combining the civilian and defence sectors. These two areas complement each other, sharing a common foundation of technological expertise in hydraulic power systems.
The Group intends to strengthen its position as Poland’s leading manufacturer and one of Europe’s foremost producers of dual-use hydraulic components, assemblies and systems. A key strategic development priority is to expand its operations into the production of complete armament systems and large-calibre ammunition. This direction reflects rising defence expenditure driven by the geopolitical situation in Europe and globally.
At the same time, the Group plans to reinforce its competitive advantages by expanding its manufacturing capacity and intensifying its research and development activities.
The Management Board has identified the following key strategic objectives for the PONAR Group:
Further strengthening the Group’s position as a leading manufacturer of hydraulic systems and hydropneumatic suspension systems for the defence sector
- International expansion in the defence sector
- Expansion of the Group’s business model into armaments production
- Scaling up operations and expanding the PONAR Group’s capabilities through acquisitions
- Growth and diversification in the civilian sector
- Technological development
“Our strategy is built on two pillars. The first is to further strengthen our position in hydraulic power solutions for the defence sector, both in Poland and internationally. The second is to expand into the production of complete armament systems. Through PK MIL, we intend to launch production of the combat-proven 155 mm BOGDANA self-propelled howitzers in Poland from 2028, which have demonstrated their effectiveness in the war in Ukraine. Meanwhile, Polska Amunicja aims to address the shortage of specialised production capacity for 155 mm artillery projectiles. These projects have the potential to transform the scale of our Group’s operations. At the same time, we are investing in manufacturing capacity and technological development, while complementing organic growth with selective acquisitions, as demonstrated by our acquisitions of ZAP-Mechanika and CASP System,” says Marek Warzecha.
PONAR Wadowice Group Financial Results
| Six months ended 30 June |
Year ended 31 December |
||||||
| (in PLN thousand)/ (audited, unless otherwise stated) |
(in PLN thousand)/ (audited, unless otherwise stated) |
||||||
| 2026 | 2025 | 2025 | 2024 | 2023 | |||
| Revenue from the sale of products, goods and materials | 244,805 | 153,718 | 351,852 | 249,882 | 206,534 | ||
| Revenue growth period-on-period (%) (unaudited) | 59.3% | – | 40.8% | 21.0% | – | ||
| Operating profit / (loss) | 55,874 | 28,794 | 68,340 | 49,680 | 30,693 | ||
| Operating profit / (loss) margin (%) (unaudited) | 22.8% | 18.7% | 19.4% | 19.9% | 14.9% | ||
| Net profit / (loss) attributable to shareholders of the parent company | 38,068 | 20,691 | 45,743 | 34,917 | 21,310 | ||
Source: The Company. Net profit (loss) per ordinary share (calculated as net profit (loss) attributable to shareholders of the parent company divided by the weighted average number of ordinary shares outstanding, excluding treasury shares). The table presents selected financial information from the consolidated statements of financial position as at 31 December 2025, 2024 and 2023.
The PONAR Group’s historical consolidated financial information as at and for the financial years ended 31 December 2025, 2024 and 2023 was audited by an independent auditor. The PONAR Group’s condensed interim consolidated financial information as at and for the six-month period ended 30 June 2026 was reviewed by an independent auditor.
In 2025, the PONAR Group’s consolidated revenue increased by 40.8% year-on-year to PLN 351.9 million. Operating profit amounted to PLN 68.3 million, compared with PLN 49.7 million in 2024 (+37.6% year-on-year), while net profit attributable to shareholders of the parent company reached PLN 45.7 million, compared with PLN 34.9 million in the previous year (+31.0% year-on-year).
In the first half of 2026, the Group’s revenue increased by 59.3% year-on-year to PLN 244.8 million. Operating profit rose to PLN 55.9 million from PLN 28.8 million, while the operating profit margin improved to 22.8% from 18.7%. Net profit attributable to shareholders of the parent company amounted to PLN 38.1 million, compared with PLN 20.7 million in the first half of 2025. The improvement in financial performance was driven by both organic growth in sales of hydraulic components and systems and the acquisitions of complementary businesses completed in the second half of 2025 and the first half of 2026.
PONAR Wadowice Group’s Order Backlog
As at 30 September 2026, the PONAR Group’s reported order backlog amounted to approximately PLN 1.7 billion. It comprised signed contracts and anticipated orders under the SAFE programme.
As at 30 September 2026, approximately 31% of the combined value of signed contracts (Fixed Backlog) and anticipated orders under the SAFE programme (SAFE-related Backlog) was attributable to
2026–2027, approximately 37% to 2028–2029, and the remaining approximately 32% to 2030 and subsequent years. At the same time, approximately 78% of the order backlog was denominated in EUR and USD, with the remaining approximately 22% denominated in PLN.
The Management Board expects further growth in the order backlog and business opportunities. The key growth drivers are expected to include: (i) the continued expansion and modernisation of the Polish Armed Forces, including, for example, the development of the KRAB2 programme and the Niedźwiedź heavy infantry fighting vehicle, for whose prototype PONAR developed a hydropneumatic suspension module in record time; (ii) securing international orders for the Group’s core military solutions; (iii) the launch and gradual commercialisation of the production of 155 mm ammunition and artillery systems; and (iv) the commencement of production and sales of 155 mm artillery projectiles.
The Management Board also sees additional growth potential in selected civilian industries, particularly the railway sector. Publicly funded investments may increase demand for the Group’s hydraulic components and systems, especially solutions for railway turnouts and loading, unloading and transport systems, in which PONAR has extensive experience.
“Recent years have been a period of rapid and profitable growth for the PONAR Group. In 2025, we increased revenue by 40.8%, and in the first half of 2026, our growth accelerated to 59.3%. We are growing while simultaneously improving profitability, with our operating profit margin consistently hovering around 20% and significantly exceeding that level in the first half of 2026. We remain focused on the quality of our financial performance, maintaining a very strong conversion of EBITDA into operating cash flow. We aim to achieve revenue of approximately PLN 500–550 million in the short term and sustain a high growth rate over the medium term. The proceeds from the share issue will enable us to finance key development projects that will further strengthen the foundations of our dynamic growth, while maintaining a prudent debt profile. We also intend to share our profits with shareholders and plan to recommend dividend distributions of at least 40% of the Group’s consolidated net profit,” concludes Marek Warzecha.